When shopping for health insurance, it’s easy to focus on one number: the monthly premium. But for 2027, Californians should pay equally close attention to what happens when they actually use their health insurance.
Covered California has released its 2027 standardized benefit designs, outlining how deductibles, copays, coinsurance, and out-of-pocket limits apply across the different metal tiers.
Meanwhile, California continues to offer Bronze, Silver, Gold, and Platinum plans, as well as Silver 73, Silver 87, and Silver 94 Enhanced Silver plans for those who qualify for Cost-Sharing Reductions (CSR). These standardized benefits also make it easier to compare coverage across insurance companies.
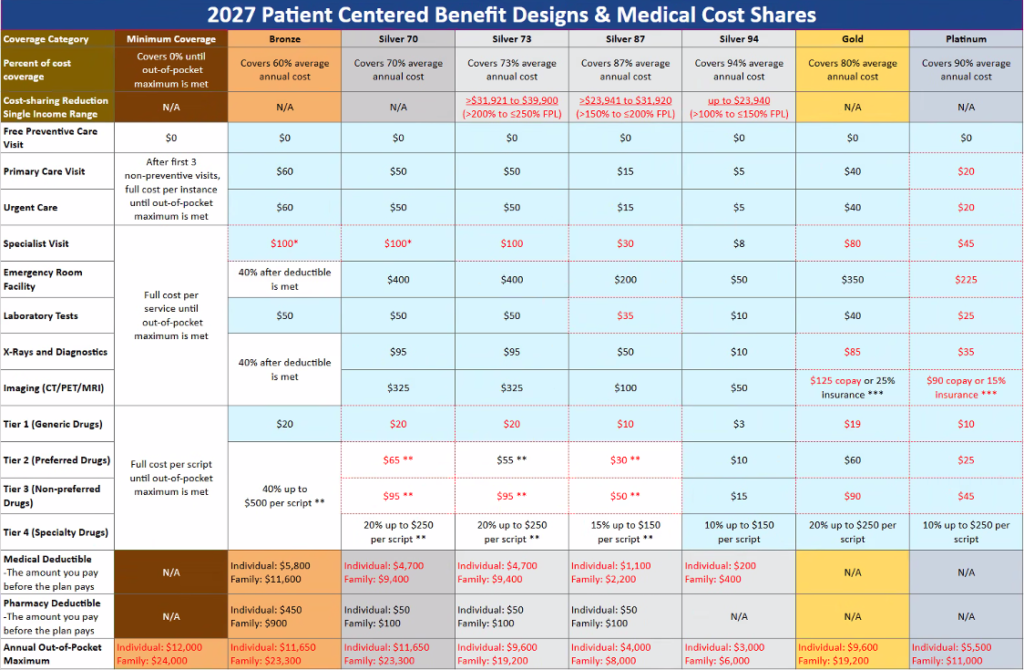
2027 California Health Plan Benefits at a Glance
| 2027 Plan | Medical Deductible | When You Use Care | Individual OOP Maximum | Key Feature |
|---|---|---|---|---|
| Platinum 90 | $0 | Lowest cost sharing | $5,500 | Richest standard benefits |
| Gold 80 | $0 | Lower cost sharing | $9,600 | Good for frequent healthcare use |
| Silver 70 | $4,700 | Moderate/higher cost sharing | $11,650 | Balance of premium and benefits |
| Bronze 60 | $5,800 | Higher member costs | $11,650 | Lower premium + HSA opportunity |
| Silver 73 (CSR) | Reduced | Reduced cost sharing | $6,100 | Enhanced benefits for those who qualify |
| Silver 87 (CSR) | Very low | Much lower cost sharing | $3,000 | Strong CSR benefits |
| Silver 94 (CSR) | Very low | Lowest cost sharing | $1,150 | Richest CSR benefits |
Benefit amounts shown are based on California’s approved 2027 standardized benefit designs. Specific carrier and plan benefits should always be reviewed before enrollment.
Silver Plans Deserve a Closer Look in 2027
The standard Silver 70 plan has a $4,700 individual medical deductible and an $11,650 individual out-of-pocket maximum for 2027. This means having health insurance doesn’t necessarily eliminate significant financial exposure if you experience a serious illness, accident, or hospitalization.
However, not all Silver plans are the same.
If your household income qualifies for Cost-Sharing Reductions, Silver 73, Silver 87, and Silver 94 can provide substantially lower deductibles, copays, and out-of-pocket maximums.
This is why it is especially important to update your projected 2027 household income and household size with Covered California. Your income can affect both your premium assistance and the benefits available to you.
Bronze Plans and HSAs
Bronze plans generally have lower monthly premiums but greater out-of-pocket exposure when you need medical care.
Importantly, Bronze plans can qualify for Health Savings Accounts (HSAs) under federal rules in 2027. As a result, eligible consumers can use an HSA to set aside pre-tax money for qualified healthcare expenses.
If you don’t use healthcare often and want to save for future medical expenses, comparing a Bronze/HSA strategy with Silver and Gold coverage may be worthwhile.
Gold and Platinum: Pay More Monthly, Less When You Need Care
Gold and Platinum plans generally have higher monthly premiums but lower cost sharing when you receive healthcare.
The standardized Gold and Platinum designs have a $0 medical deductible, which can make them worth comparing for people who see specialists regularly, anticipate procedures, or simply prefer more predictable medical expenses.
A higher premium doesn’t automatically mean a plan will cost you more over the entire year. What matters is your total healthcare spending.
Could Supplemental Indemnity Coverage Help With the Gap?
With some ACA plans carrying thousands of dollars in potential out-of-pocket exposure, another option is supplemental accident or hospital indemnity insurance.
First, how high is my deductible? Next, how much could I potentially pay out of pocket? Finally, are my prescription drugs covered, and what will they cost?
That money can help with expenses such as your deductible, copays, and other costs that arise when an unexpected medical event occurs.
If you choose a higher-deductible Bronze or Silver plan, adding supplemental out-of-pocket maximum protection may be worth reviewing as part of your overall insurance strategy.
Important: Accident and hospital indemnity policies are supplemental insurance. They do not replace ACA-compliant major medical health insurance, and benefits, limitations, and exclusions vary by policy.
Don’t Choose Your 2027 Plan by Premium Alone
When your renewal arrives, instead of asking only “How much is my premium?”, also consider:
How high is my deductible? How much could I potentially pay out of pocket? Are my prescription drugs covered, and what will they cost? Are my doctors and hospitals in-network? Do I qualify for Enhanced Silver benefits? Would an HSA or supplemental indemnity plan help protect me financially?
The least expensive plan each month isn’t necessarily the least expensive plan when you actually need healthcare.
At Solid Health Insurance Services, we can help you compare the full 2027 benefit structure—including your premium, deductible, doctors, prescriptions, and potential out-of-pocket exposure—and help you understand your options.
Your Health Matters! Your Budget Matters!